Spring into a new home
JOEL MARTIN | Hagadone News Network | UPDATED 7 months, 3 weeks AGO
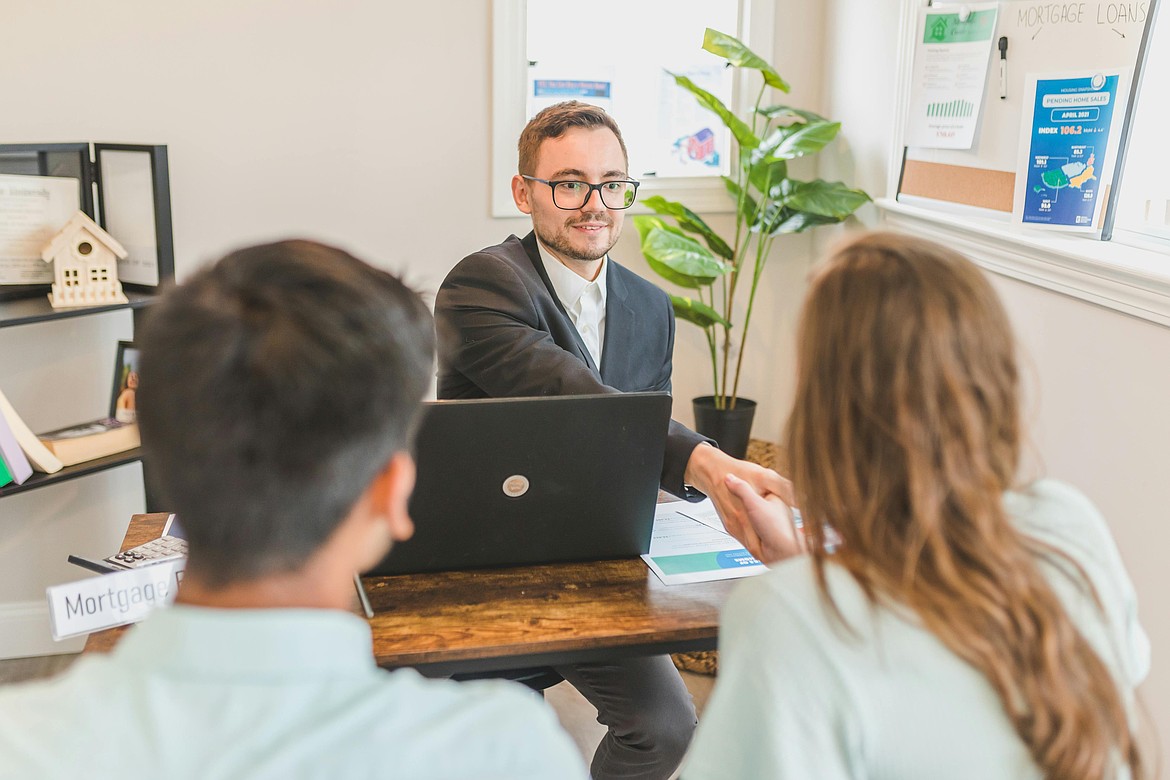
Spring is a good time to sit down with a mortgage professional to discuss buying a home.
COURTESY PHOTO/RDNE STOCK PROJECT/PEXELS
Joel Martin has been with the Columbia Basin Herald for more than 25 years in a variety of roles and is the most-tenured employee in the building. Martin is a married father of eight and enjoys spending time with his children and his wife, Christina. He is passionate about the paper’s mission of informing the people of the Columbia Basin because he knows it is important to record the history of the communities the publication serves. | February 27, 2026 12:30 AM
MOSES LAKE — Spring is just about here, and that’s the prime home-buying season, said Steve Tagnolli, vice president of home loans at Gesa Credit Union.
“Traditionally, it gets busier in March, April and May,” Tagnolli said. “There’s not many people who want to relocate during the holidays, not only because it’s the holidays but because of the weather in the wintertime.”
Between 60% and 70% of home relocations take place during the summer months, according to Moving.com, both because the weather is better suited and so children can start a new school at the beginning of the school year. That means now is the time to talk to a home loan professional. Tagnolli said.
“The best thing they can do is, three-to-six-months ahead of time, meet with a value-added advisor who can put them in a position to qualify to achieve that dream,” he said.
The first step is to get pre-qualified, he added. Pre-qualification means a lender is tentatively willing to lend the borrower up to a certain amount of money. It’s not a guarantee, according to the Consumer Financial Protection Bureau, but it does give the prospective home buyer an idea of how much they can spend when they begin looking at homes in earnest.
The home loan advisor will do a soft pull on the buyer’s credit report, meaning the check is free and doesn’t affect the buyer’s credit score. Then they’ll look at things like income, expenses and debt.
“Do you have a car payment?” Tagnolli said. “What is your insurance? What is your current rent payment? Until (people) sit down with an advisor like that, sometimes they don't understand what their monthly obligations are.”
A major factor will be the borrower’s debt-to-income ratio, the percentage of gross income – pretax earnings, Social Security, rental property income – that’s spent on recurring debts like rent, child support, credit cards and loans, according to Bankrate.com. The lower the DTI ratio, the better your chances of being approved for a loan. A lower ratio can also enable you to get a better interest rate on a mortgage.
A higher DTI ratio doesn’t necessarily put a borrower out of the running, Tagnolli said.
“(With) a lot of conventional loan programs, the DTI (required) is 43% but there's a lot of portfolio lenders, banks, credit unions (that) can go up to 50% DTI,” he said. “That's another reason they should meet with a home loan officer so we can articulate and explain to them how that works.”
Many people start off with the assumption that they need to have enough money in the bank to put down 20% on a loan, but that’s not the case, Tagnolli said. There are programs that will allow a buyer to buy a home with lower or even no down payment, although that may mean a higher interest rate and hence a higher monthly payment.
“That’s why it benefits them to meet with a home loan officer,” Tagnolli said.”We can tell them ‘If you put 20% down, this is your payment. If you only put 10% down, your payment would be a little higher because of this and this.’”
There was a time when the conventional wisdom was that a buyer should go for the most home they can afford, but that’s not the case any longer, Tagnolli said.
“A lot of economists felt like home values are going to appreciate over time, so it's a great investment in your future,” he said. “It's not just a place to live, but it can be a great investment. But the market always changes. There's ups and downs … Sometimes people find a good house on Zillow, but (it’s not a good fit) given where they are in their life. Do they have kids? Are the kids almost out of the house? Do they want single-level? Do they want two-story? … People have come back 15 years later and said, ‘I wish I bought a single-level house, because now I'm in my 60s. I'm getting close to retirement, and my bedroom’s upstairs.’”
The big mistake many people make is assuming they can’t afford a home, and never will. That’s something a mortgage professional can help with, Tagnolli said.
“One of the most rewarding things we've experienced is meeting with a (potential borrower) today, advising them on the process and then seeing them come back a year from now and qualify for a home loan,” he said. “The local banks and credit unions in the Northwest, we all provide that service for free. They can get a free consultation anywhere, and if they're not qualified today, we can tell them what they need to do to qualify in the future.”
ARTICLES BY JOEL MARTIN
Endless battle
Noxious Weed Control Board works to keep invasive plants under control
MOSES LAKE — Some of the nastiest plants in Grant County were the topic of a class led by Jay Johnson, a consultant with the Grant County Noxious Weed Control Board, Tuesday. The Noxious Weed Control Board, as its name would suggest, is tasked with keeping weeds under control in Grant County. That’s not a small job; the board’s website lists 129 species of noxious weeds that are found around Grant County. A noxious weed is defined as an invasive, non-native plant that threatens agricultural crops, local ecosystems or fish and wildlife habitat, according to the Noxious Weed Control Board. Washington state law requires that these weeds be identified and their spread kept to a minimum, if not completely eradicated. “We’re one of those agencies a lot of people don’t really understand,” Johnson said. “We’re a county office and … our funding is tax-based assessment. When you get your tax bill and you look down at all the expenses that you pay for, there we are.”
BASIN EVENTS: Oct. 16-24
COLUMBIA BASIN — Whether you feel like shopping, crafting, learning or seeing a show, there’s something happening for you this week in the Basin. Oct. 16 ‘My Family (Mi Familia)’ screening Spanning three generations, “My Family (Mi Familia)” is a heartfelt drama that follows the Sánchez family as they build their lives in East Los Angeles. Through love, hardship, triumph, and sacrifice, the film explores the immigrant experience, the strength of family bonds, and the traditions that connect one generation to the next. Lowrider show and taco truck before the screening. Sponsored by Columbia Basin Allied Arts, EDUBS C/S and the Moses Lake Creative District. $12 per person. Doors open at 6 p.m., film begins at 7 p.m. at the Moses Lake Civic Center Auditorium, 401 S. Balsam St. Tickets and info: www.cba-arts.org.
Moses Lake author encourages women to look beyond church culture norms
MOSES LAKE — A Moses Lake author’s book, “A Christian Woman Striving to Live Her Faith in a Man-Controlled World,” takes aim at the role to which many churches relegate the female half of their congregations. “It’s to encourage women in the faith,” Linda Curran said. “A lot of churches say, ‘Teach Sunday school, do this, do that, but don’t (evangelize.)’" In her book, Curran recounts a time when she moved to a new community and joined a church there. She was surprised to learn that, as a new female member, she had been automatically assigned church cleaning duties. When she questioned it, she wrote, she was met with condescension and her objections were brushed aside. In other churches, she said, women who were capable of teaching were relegated to “women’s ministry.”